

A Bitcoin investor can withdraw coins from an exchange, return them to the same account, and still fall outside mandatory cost-basis reporting when those coins are sold.
For the 2026 US reporting year, the broker can still be required to report sale proceeds, while reporting the acquisition cost remains voluntary.
Cost basis, the acquisition cost used to calculate a gain, only changes the broker’s obligation to supply an ordinary transfer between the investor’s own accounts. That creates a practical divide between a record showing how much a sale brought in and one that supports the gain calculation.
The IRS’s 2026 Form 1099-DA instructions make that divide explicit. Covered digital assets generally must have been acquired after 2025 in the reporting broker’s custodial account and held there until disposal. Assets bought before 2026 or transferred into the broker are noncovered, with basis reporting voluntary.
The distinction runs through the current reporting year as international reporting develops and blockchain analytics providers offer tax authorities a wider view of activity.
Three routes, the same gain
Consider a deliberately simplified hypothetical US investment: 0.1 Bitcoin bought for $5,000 in February 2026 and sold for $7,000 in September. Assume one purchase lot, unchanged ownership, no intervening trades, no fees, and no other basis adjustments.
The purchase and sale stay identical across three paths, only the custody route changes.
| Custody route | 2026 reporting classification | Basis and gain in this example |
|---|---|---|
| Bought and continuously held with the selling broker | Covered; mandatory basis reporting | $5,000 basis; $2,000 gain |
| Bought with one broker, transferred to another and sold | Noncovered; basis reporting voluntary | $5,000 basis; $2,000 gain |
| Bought with a broker, withdrawn to an owned wallet, returned and sold | Noncovered; basis reporting voluntary | $5,000 basis; $2,000 gain |
The third path is the easiest to miss. Returning to the original account does not satisfy the continuous-custody condition. A broker may have recorded the original purchase, but that does not make returned coins continuously held assets under the reporting definition.
For the investor, each hypothetical sale still produces the same $2,000 gain. A blank basis field cannot be read as a $7,000 gain, so the missing information on the form does not determine that the acquisition cost was zero.
The IRS’s digital-asset FAQs explain why the wallet movement itself does not change that result: transferring assets between accounts or wallets belonging to the same taxpayer is nontaxable, except for digital assets used or withheld to pay for transfer services.
Fee coins can create a separate disposal, which is why the comparison deliberately excludes fees.
Outside applicable optional reporting methods, the form includes fields for transferred units subsequently disposed of and their transfer-in date, with a date exception for transfers on varied dates. Sale proceeds can be reportable even when basis is not mandatory.
Coinbase’s current guidance distinguishes its proceeds-only 2025 forms from basis information beginning in tax year 2026 for certain assets. It also tells customers to retain records from other accounts and wallets. That qualification matters: the change does not promise a completed basis record for every sale.
Kraken’s guide to its 2025 combined forms, updated March 30, describes a more specific split. Customer copies showed estimated basis and gains or losses using FIFO, or first in, first out. What was sent to the IRS was the gross proceeds.
The same guide says Kraken tracks basis for activity within the same account, does not track what happens outside it, and treats returning assets as a new deposit without automatically restoring their previous basis.
For the unchanged lot in this hypothetical, recording its return as a new deposit does not create a new acquisition cost. The original purchase record remains relevant even if the returning deposit lacks an automatically attached basis.
This distinction gives investors three separate questions to resolve: what the platform displays, what it reports to the authority, and what their full transaction history supports. A convenient gain estimate may answer only the first.
Why a wider Bitcoin transaction trail still needs acquisition records
International reporting addresses a different part of the problem. The OECD’s Crypto-Asset Reporting Framework (CARF) provides for annual exchange of crypto-transaction information with taxpayers’ residence jurisdictions through domestic rules and exchange arrangements. It is separate from US Form 1099-DA and does not create a single worldwide crypto tax bill.
The UK offers a concrete timetable. HMRC’s guidance calls for user details and transaction summaries, with the first provider report due between Jan. 1 and May 31, 2027, covering calendar 2026.
That reporting can reveal transactions without attaching the acquisition history needed for every investor’s gain.
Blockchain analytics extends the question beyond broker submissions. In an Aug. 26 research preview, Chainalysis estimated more than $457 billion in potentially taxable on-chain activity during 2025, including approximately $112.6 billion attributed to the US.
The commercial analytics provider says it covers Bitcoin, Ethereum, Solana, Tron, BNB Smart Chain and Base, assigning countries through direct location signals and proportional allocation based on service activity.
Its estimate excludes trading, staking, and lending conducted inside centralized exchanges and does not apply some countries’ transaction or income exemptions. Missing activity restricts coverage, while unapplied exemptions prevent treating every estimated dollar as taxable in its assigned jurisdiction.
Address tracing can help connect movements. However, a path between addresses does not establish an investor’s purchase price, unchanged ownership, chosen acquisition lot or subsequent adjustments.
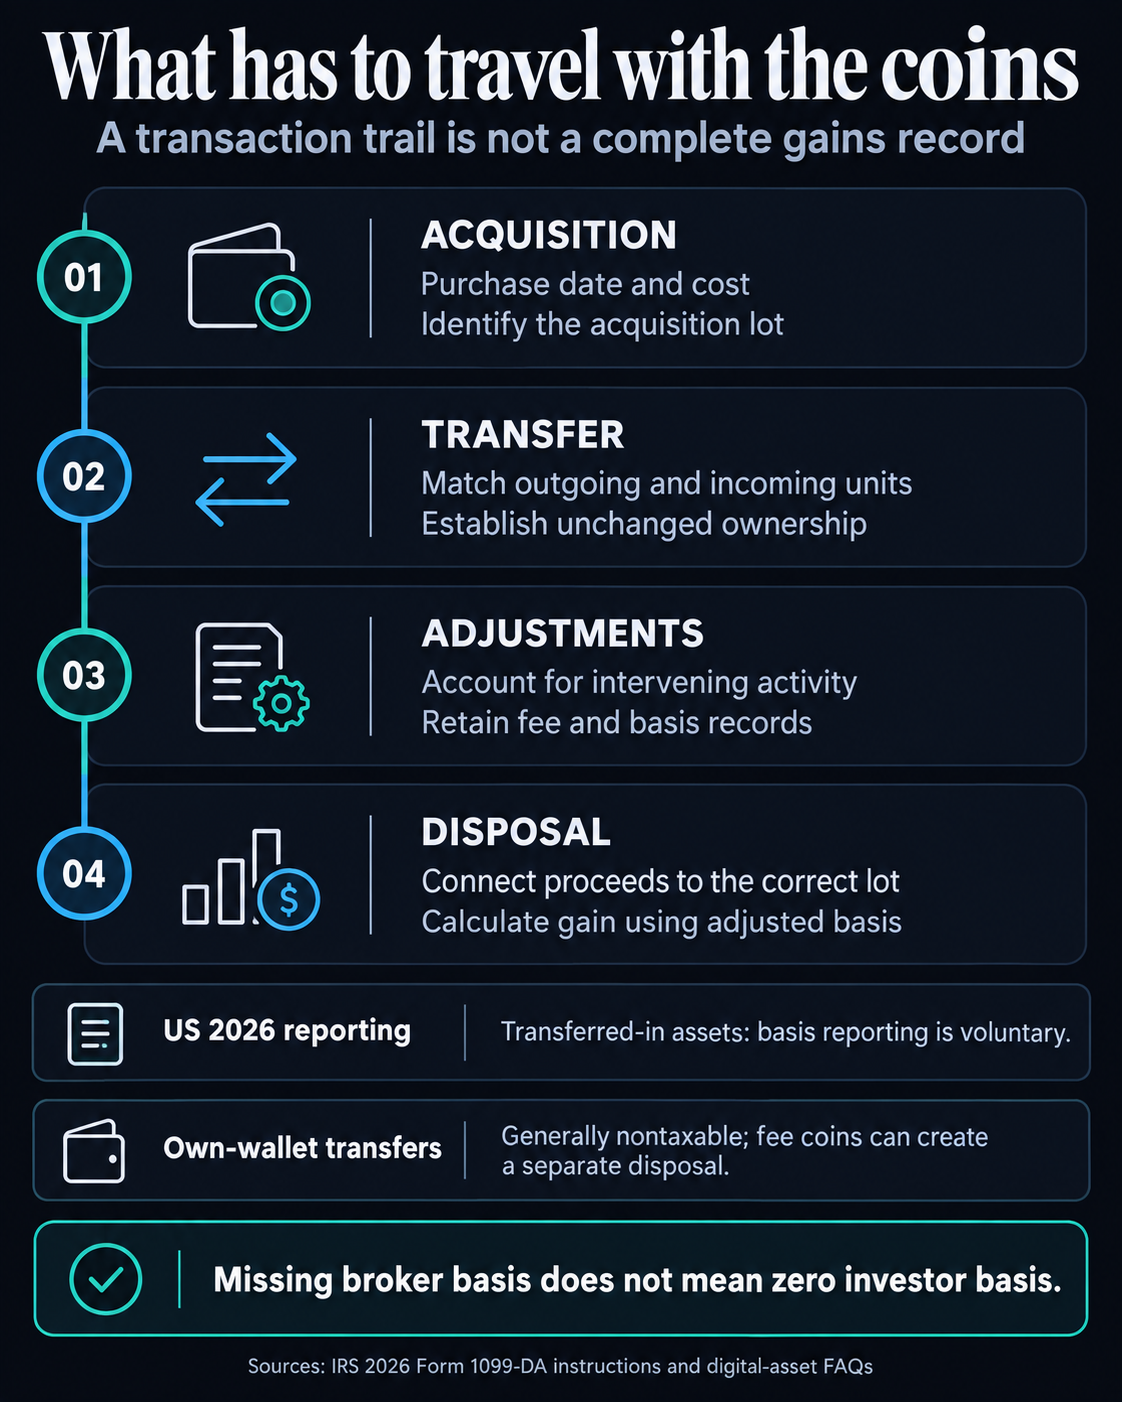
For the US investor in the three-route comparison, a usable gains record needs continuity of information and continuity of ownership. In the three-route example, the crucial connection is between the original $5,000 purchase and the eventual disposal. An incoming transfer’s date and quantity alone do not make that connection.
Better interoperability would need to preserve acquisition details, match outgoing and incoming transfers, and account for intervening disposals and adjustments. That could reduce reconstruction work without requiring every investor to remain in one account. Sharing those records would not make the transferred lots continuously held assets under the current rule.
For relevant partial disposals after 2025, IRS FAQ 85 requires investors using specific identification to identify units to the custodial broker by transaction time using its designated identifiers and retain substantiating records. A later spreadsheet choice does not substitute for timely identification.
The reporting rules also contain exceptions: eligible optional methods for qualifying stablecoins and specified NFTs can omit basis even for covered assets, and certain categories have reporting thresholds. Assess a form’s completeness based on the method used.
The available disclosures establish why more reporting can coexist with unfinished records. For a transferred holding, calculating the gain still means connecting the sale to the original acquisition, the correct lot, and any subsequent adjustments.


